
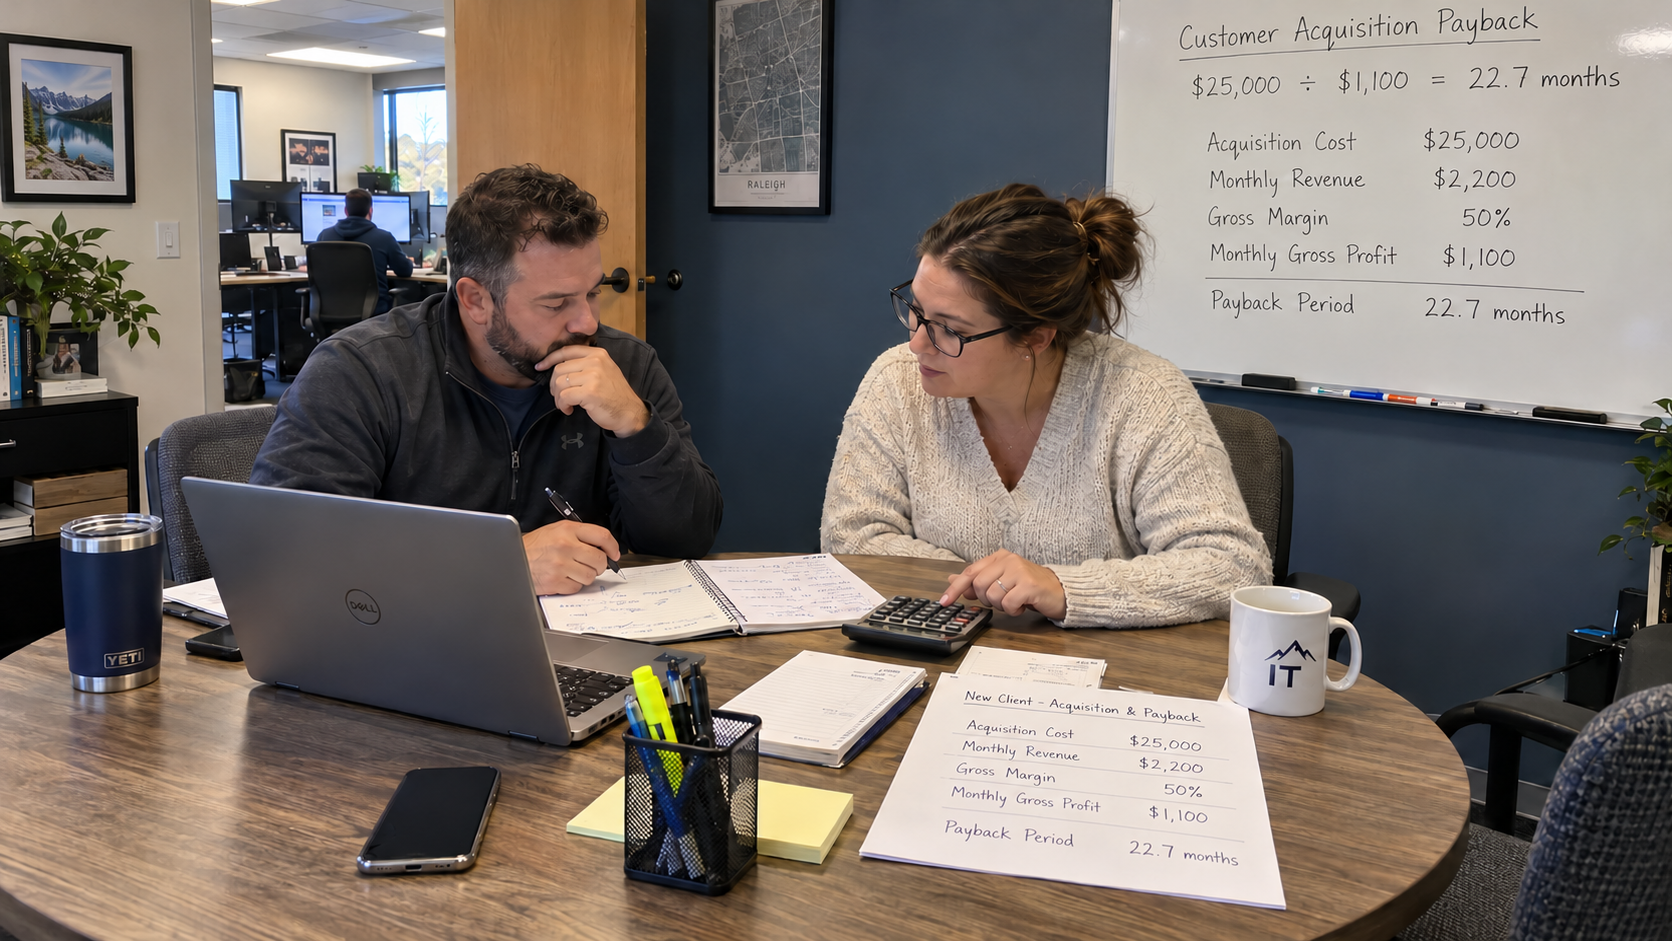
A signed agreement hasn't repaid your MSP customer acquisition cost. In the MSP model, calculate acquisition payback as $25,000 ÷ ($2,200 × 0.50), or about 22.7 months. I'd want that number beside the sales results before approving more acquisition spending.
The starting assumptions are $2,200 in new-client MRR and a 50% managed services gross margin. Monthly gross profit is $2,200 × 0.50 = $1,100 after modeled service delivery costs. Divide the acquisition cost by that amount, and you have a simple gross-profit payback period, before separately counting unpaid onboarding.
Give Acquisition Cost a Consistent Definition
Client acquisition cost, or CAC, is sales-and-marketing spending divided by new clients won over the period you're measuring. Count the people doing the work as well as the campaigns. In the model, the $25,000 assumption covers the whole sales-and-marketing budget allocated across the new managed clients.
That allocation is different from asking what the next deal will cost in cash. A rep already on payroll can close another agreement without you paying their annual salary again. Keep that distinction when you compare a marketing proposal with the business's actual cash commitments.
I'd start with your accounts and signed-client records, rather than a campaign dashboard. Reconcile the spending total with finance, then reconcile the client count with the agreements. Put the start date and starting MRR beside each win so you can see what the spend actually brought in.
Use the same definition from one comparison to the next. If one campaign's calculation includes staff pay and another includes only advertising invoices, the apparent difference reflects the costing method as well as the results. Decide what each comparison includes before choosing what to cut.
Use Gross Profit From the New Agreement
Gross profit is service revenue less the costs of delivering that service. For this calculation, use the model's 50% managed services target, including burdened delivery labor and tools. Don't divide CAC by the entire monthly fee, because the fee also has to fund delivery.
| Input or Calculation | Model Assumption or Result |
|---|---|
| Acquisition cost per new managed client | $25,000 |
| Starting managed services MRR | $2,200 |
| Fully loaded managed services gross margin | 50% |
| Monthly gross profit: MRR multiplied by margin | $2,200 × 0.50 = $1,100 |
| Acquisition cost divided by monthly gross profit | $25,000 ÷ $1,100 = about 22.7 months |
The model's existing clients average $4,500 MRR, which is higher than the starting amount for a new client. Substituting that book average would shorten the calculated wait by assuming revenue the new agreement hasn't started with. Use the starting fee first, then update the calculation when the account actually changes.
Keep the revenue and costs on the same basis. If an invoice includes separately resold licenses, separate their revenue and cost before calculating managed services payback. Applying the service margin to an invoice that includes a different revenue line would give you the wrong monthly contribution.
Gross profit also comes before general overhead and your fair-market owner salary. Reaching acquisition payback therefore doesn't establish that the client has produced that amount of EBITDA. It tells you when the modeled gross profit has accumulated to the acquisition amount you chose to recover.
Put Free Onboarding Beside the Sales Cost
The model quotes onboarding and then waives the fee for a signed agreement. It still allows 60 hours of project-engineer work per new client. That labor sits in project delivery, so it won't appear merely because you totaled the marketing accounts.
Make a separate onboarding cost calculation using the actual hours and the project team's burdened productive-hour cost. Then check where that cost already appears. If your CAC includes it, or your monthly client-cost allocation already recovers it, don't add the same cost again.
For a calculation that keeps onboarding separate, add the unrecovered onboarding cost to the acquisition amount before dividing by monthly gross profit. Label the result acquisition-and-onboarding payback. Keeping both results visible shows what changed without quietly redefining CAC.
Here is what I'd cut from the report: any claim that onboarding was free because the invoice was waived. Show the project hours and their cost instead. You can still choose the concession while budgeting for the people who deliver it.
Check Whether the Client Stays Long Enough
The simple payback calculation assumes the monthly gross profit continues. If the client leaves, stop adding future months and total what was actually earned. Compare that accumulated gross profit with the acquisition and onboarding costs still to recover.
The model's 95% annual retention assumption describes the book as a whole. It doesn't establish how many recently signed clients will remain through their own payback period. Check new-client retention separately before using the overall rate to defend an acquisition plan.
I'd group clients by when they started and compare what has happened since. Record changes in recurring fees alongside the delivery cost and any termination date. An account that hasn't been with you through the modeled payback period still needs observation; don't count its assumed future margin as recovered spending.
A change in retention after a new process is a reason to investigate, not proof that the process caused it. Compare the client mix and account circumstances before crediting a campaign or a handoff change. Keep the measurement attached to the clients whose payback you're assessing.
More Spending Buys a Pace, Not a Shorter Wait
In the model, increasing sales and marketing from 6% to 10% changes the number of clients the budget supports. It holds acquisition cost per client and starting MRR constant. With those inputs and margin unchanged, the same per-client payback calculation applies.
To shorten the calculated payback, change an input rather than the budget label. Lower acquisition cost shortens the wait if monthly gross profit stays the same. Higher starting MRR or a higher margin does the same if the other inputs hold.
Those conditions matter when you choose a prospect. A larger fee doesn't automatically mean faster payback if delivery costs or the acquisition spend also rise. Recalculate the whole relationship before telling the team to chase larger contracts.
My view is that marketing cannot repair a delivery plan that doesn't earn enough margin. Follow the model's order: fix service delivery before adding clients. If recorded labor shows an agreement requires more work than its price allows, address that cost and scope before buying more of the same business.
Turn the Calculation Into a Spending Decision
Keep the simple payback estimate beside a cash forecast. The estimate uses allocated costs and monthly gross profit; the forecast needs actual collection and payment dates. Test whether the business can meet its commitments while those client contributions accumulate.
Before the next spending decision, I'd have the owner and the person responsible for finance agree on these checks:
- Reconcile acquisition spending and signed clients using the same period and cost definition.
- Calculate starting monthly gross profit from matching service revenue and delivery costs.
- Identify unpaid onboarding once and show whether it is inside or outside the payback amount.
- Compare accumulated gross profit and retention for clients that have reached the relevant age.
- Check the collection forecast before committing cash to another campaign.
If the result is longer than the model's example, use the inputs to decide what to inspect. The calculation alone doesn't tell you whether the issue is prospect fit, sales execution, or service cost. Change the spending decision when the underlying evidence changes, rather than treating a lead count as repayment.
mspoutpost.com/articles/msp-customer-acquisition-cost-calculate-your-payback
Written by Owen Gallagher
MSP Outpost publishes information, not legal, financial, insurance, tax or compliance advice, and reading it creates no professional relationship. For decisions about your business, talk to a qualified professional.