Figures are in US dollars unless marked.
Should I sell my business or close it? Take a hypothetical US MSP with $730,276 of annual EBITDA after paying the owner a fair market salary. That salary for running the place costs $240,000 x 1.13 = $271,200 a year. Keep that job in the sums before you compare an exit with handing the MSP to a manager.
EBITDA is earnings before interest, taxes, depreciation and amortization. It isn't what you get to spend after a sale, and it isn't cash you can just take out while you keep the business. I'd compare each option on the money you end up with and the work you're still on the hook for.
Decide What You Need Before Choosing an Exit
Write down what you need this decision to give you. Keep the lump sum you need apart from the yearly income you want. Be honest about how much of the running you're willing to keep, instead of calling any shorter week a full exit.
Nick Bartolo says his firm asks sellers to tie the decision to the money left after tax and the life they want afterward. He contrasts that with selling right away because the business is going through a rough patch. That's his account of how they plan, and it's a good first question for your own comparison.
Work out that number from your own situation. Keep the assumptions where you can see them, so you can redo it when a deal changes. A headline price on its own can't tell you whether you'll walk away with enough.
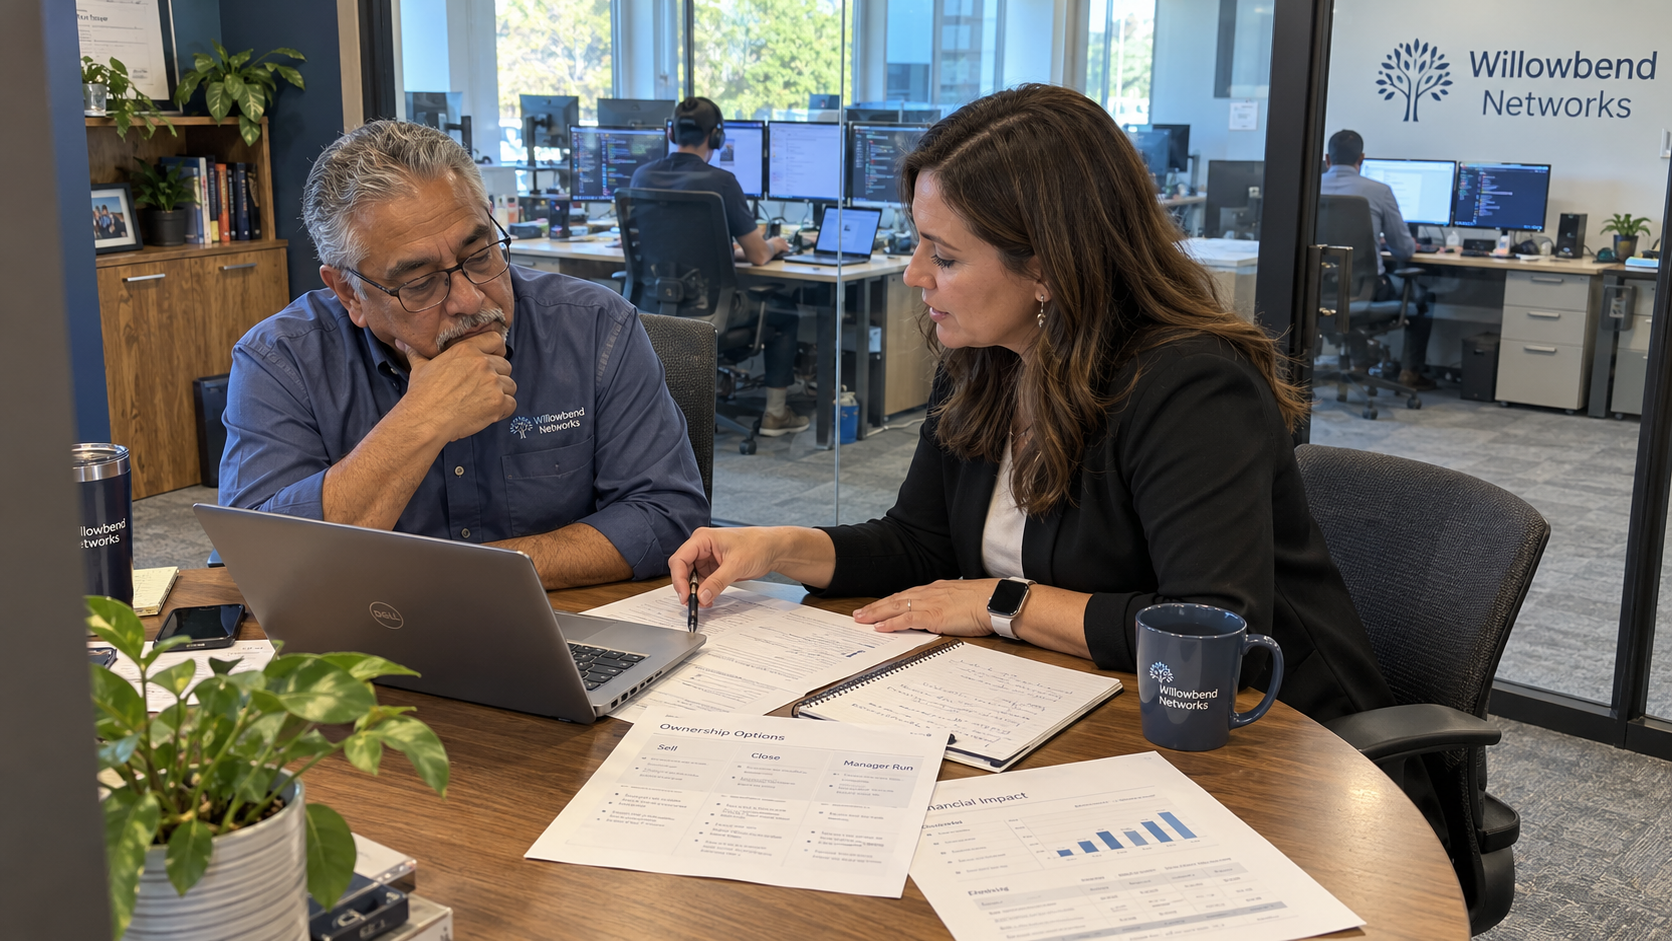
I'd fill in the comparison below before picking a route. It keeps selling the whole business apart from arrangements where you still own the risk.
| Option | What to Work Out | What It Still Asks of You |
|---|---|---|
| Sell the Business | What you actually walk away with after the buyer's adjustments, debt, costs and tax, split by when each payment arrives. | Negotiating the handover, then any transition work or ongoing duties you agree to. |
| Close the Business | Cash you can actually collect and what your assets will really sell for, less what it costs to wind down properly and pay what you owe. | Seeing clients and staff through to the end of the closure work you agree. |
| Keep It With a Manager | Cash you can take out after the real cost of a manager and what the business needs to keep running. | You still own the risk, plus however closely you agree to keep watching it. |
Work Out What a Sale Puts in Your Pocket
Buyers typically value an MSP on its earnings, and they discount revenue that doesn't recur. For the hypothetical US MSP, use the typical US multiples from the 2025 seller's market: 4.75x at $500,000 of EBITDA and 6.5x at $1,000,000, with a straight line between them. At $730,276, that gives 4.75 + (6.5 − 4.75) × (($730,276 − $500,000) ÷ ($1,000,000 − $500,000)) = 5.555966x, so $730,276 × 5.555966 = about $4.06 million for the business. That dated multiple isn't a buyer's offer today, and it isn't what lands in your account.
That figure is the price for the business itself, before the deal sorts out cash, debt and other agreed adjustments. Walk that number down yourself to what the buyer actually pays for your shares. Then take off the fees, and get your accountant to confirm the tax on what you keep.
Keep the money you get at closing apart from money that comes later. If a payment depends on how the business does after you sell, write that condition next to it. Don't plan your life around money that might not come.
Use the real offer terms to say what work you'd still owe. If a buyer wants your time, put down how much and for how long. A higher price can still ask more of you than the exit you wanted.
My view is to build value from recurring, profitable revenue that doesn't depend on you. Check how close your business really is to that before you lean on a typical valuation. The test is the work the business keeps delivering without you, not how good you feel about your client relationships.
Work Out What Closing Down Leaves You
Build a closing cash plan from what you actually owe. Start with the cash you have and what you can really collect or sell your assets for. Then take off what it costs to finish the closure and pay what's left.
Don't count client-owned equipment as something you can sell. Check who owns what, and what the agreements say, before you put a number on it. Give doubtful invoices their own line instead of counting every one at full value.
Go through each contract and list the work to hand that client over. Keep your service and supplier commitments in the cash plan until you know how each one ends. Deleting a cost from a spreadsheet doesn't end the contract behind it.
The SBA's Close or sell your business guidance recommends getting a lawyer and getting the business valued when you plan a closure. It lists paying off what the business owes among the steps. Get your lawyer to confirm what closing legally involves for your kind of company and where you are. Keep those costs in the comparison, rather than assuming closing is the option with no paperwork.
Give each closing job to a named person. Your team needs a plan to hand over client information and sort out equipment. Price the work that carries on during that time before you say what's left for you.
Price a Manager Before Assuming You Can Step Back
The hypothetical MSP's $730,276 of EBITDA already has the $271,200 manager's salary taken out. If someone else does that same job at that cost, don't take the salary off a second time. If the job, or covering what you did, costs more, add the extra and redo the earnings.
Count your own tech work too. My view is that hours you spend as a tech count as direct labor. Moving a salary you already pay into delivery changes your service margin; paying for work nobody was covering changes your total earnings.
Write down what the manager decides and what still needs you. Ray J. Green recommends spelling out the day-to-day work, what good output looks like and what the role expects before you hire. That's his advice from running his own hiring, and it's worth using to describe a real job rather than hoping one capable person will take everything off your plate.
Watch how the work runs once you actually hand decisions over. Note every task that comes back to you and why it couldn't get done. A manager title is a rather expensive assumption if you still do the job.
Then turn earnings into the cash you could actually take out. Keep the investment and money the business needs to run where you can see it. Owning it can pay you an income, but you also keep riding whatever happens to it next.
Decide Using the Same Books for Each Option
Use the same books and the same date for each option. Pick out the assumptions that would change your mind, then find real numbers for them. A written sale offer and a manager's salary quote count for more than a rule of thumb about what owners usually do.
Don't just add money you'd get now to years of income you might get later. Weigh when each payment comes and how likely it is to arrive. Use your own idea of an acceptable payback rather than borrowing somebody's standard one.
If the sale doesn't leave you enough after tax, work out whether the problem is the price or the terms. If the manager option doesn't work, find the work or cost that keeps it tied to you. If closing looks best, check what you still owe under each contract before you treat that as settled.
Start with your earnings after a fair salary for you, and the jobs you still actually do. Build the cash picture for each real option yourself, then put the work left for you next to each result. Choose from those, rather than letting the biggest headline number decide for you.
mspoutpost.com/articles/should-i-sell-my-business-or-close-it-compare-options
Written by Graham Whitfield
MSP Outpost publishes information, not legal, financial, insurance, tax or compliance advice, and reading it creates no professional relationship. For decisions about your business, talk to a qualified professional.