
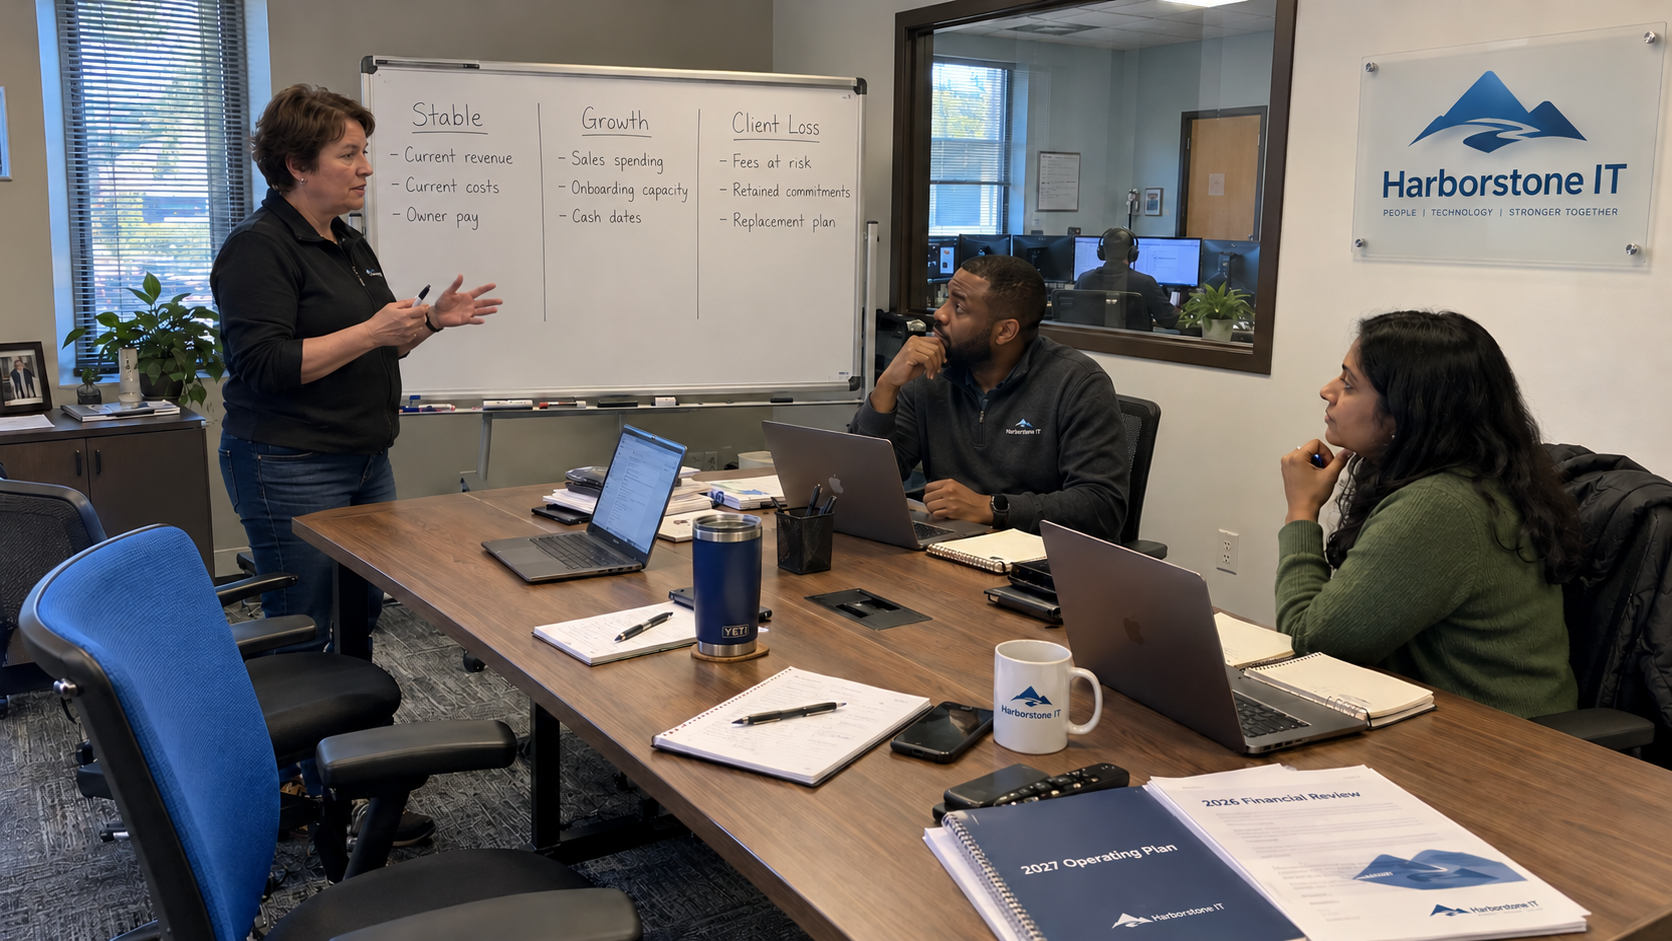
Financial scenario planning should show which commitments your MSP can keep when sales spending rises or clients leave. Build the cases from the same accounts and operating assumptions, then change the named inputs. Compare earnings, cash dates, and delivery capacity before committing to a hire or a larger lease.
A scenario is a defined set of assumptions, not a probability assigned to the coming year. I'd keep a stable case, a growth-investment case, and a client-loss case beside one another. The useful output is a decision that survives the relevant cases, or a clear condition that must be met before you commit.
Use the Same Starting Business
Begin with revenue by line, delivery costs, sales spending, and administration. Include fair-market owner pay before counting profit. Record the dates and commitments behind the numbers so the downside case doesn't quietly assume costs disappear with revenue.
The MSP Outpost model's US example has 700 seats across 35 clients at $225 per seat each month. Its total annual revenue is $3,634,615. The model prices a stable setting and a growth setting against that same starting business, so their difference first shows the cost of buying growth.
Keep your own cases on the same basis. If one includes future sales and another uses current revenue only, make that difference explicit. Otherwise a higher profit line could simply mean you added optimistic revenue to one column.
Compare the Stable and Growth Settings
The stable setting spends 6% of revenue on sales and marketing. The growth setting spends 10%. Both percentages include the relevant sales and marketing pay, so adding the marketing hire again would overstate the cost.
| Annual Line, US Model | Stable Setting | Growth Setting |
|---|---|---|
| Starting revenue | $3,634,615 | $3,634,615 |
| Sales and marketing | $218,077 | $363,462 |
| Project labor, onboarding included | $155,908 | $181,873 |
| General and administrative costs | $646,602 | $661,445 |
| EBITDA | $730,276 | $544,083 |
| EBITDA margin | 20.09% | 14.97% |
The EBITDA difference is $186,193, calculated as $730,276 minus $544,083. Sales and marketing accounts for $145,385 of that difference. The remaining $40,808 comes from additional project labor and administration, using the displayed model figures.
This is a cost comparison on the same starting revenue. It doesn't mean an actual growth year earns no additional revenue. Add signed and expected new business separately, with its start dates, delivery costs, and confidence recorded.
Then test the project team. The model puts unpaid new-client onboarding on project engineers rather than the support desk. Higher acquisition spending doesn't create onboarding capacity by itself; the delivery plan needs to show who can do that work alongside billed projects.
Build the Client-Loss Case From Actual Accounts
Use named internal account records for your real forecast. Identify the fee lost, likely timing, remaining delivery obligations, tool commitments, and any related product or project revenue. Keep this detail private within the planning file rather than treating all clients as identical.
For an illustration, remove two of the example's 20-seat clients at its $4,500 average monthly managed-service fee. The annualized seat-fee exposure is two times $4,500 times 12, or $108,000. That is the full-year effect of the missing fees; a departure partway through your plan changes the timing.
Those clients represent 40 seats. If the model's $22.50 monthly tool cost per seat could stop with all of them, the annualized tool reduction would be 40 times $22.50 times 12, or $10,800. Check actual supplier commitments before using that saving in a cash forecast.
For a limited comparison, hold payroll and every other revenue and cost line unchanged. The net earnings reduction is then $108,000 minus $10,800, or $97,200. Applying that to the stable example's $730,276 gives $633,076 before any other consequences of the departures.
That limited bridge isolates the managed-service fee and tools. It isn't a complete client-loss forecast: related license sales, projects, offboarding work, delayed collections, or retained tool commitments can change the result. Add those account-specific items before deciding which commitments remain affordable.
Separate Freed Work From Money Saved
The lost clients may free delivery time while payroll stays in place. Don't reduce the salary line simply because your allocation reports show fewer hours against those accounts. Record the capacity released and what you intend to do with it.
That capacity might support a signed replacement client or existing project work. Until the replacement starts, keep its revenue out of the committed-cash view. A sales opportunity and an occupied technician are different forms of certainty.
Justin Esgar, in a practitioner supplier-terms account, describes a vendor arrangement that retained a higher committed quantity after temporary users departed. His example illustrates why you should inspect actual terms. It doesn't establish that every supplier uses the same commitment rule.
Have the bookkeeper put cancellation dates and retained charges beside each proposed saving. Have the service lead record offboarding work and available delivery capacity. The owner can then see which changes affect cash and which affect the work schedule.
Attach Decisions to Conditions You Can Verify
Compare the cases before issuing the offer or signing the lease. Where a commitment fits only the growth case, identify what must be true to fund it. State the evidence required, such as a signed agreement, available delivery coverage, or confirmed cancellation of an existing expense.
| Decision | Check Across the Cases | Record Before Committing |
|---|---|---|
| Add a delivery role | Work needed, coverage available, and payroll timing | Accepted responsibilities, start date, and funded cost |
| Increase acquisition spending | Spending already committed and delivery needed for wins | Campaign ownership, tracking, and onboarding capacity |
| Expand office space | Recurring occupancy change and one-time payments | Terms, payment dates, and costs that remain |
| Replace lost revenue | Expected start, fit, and full delivery effort | Signed work distinguished from pipeline assumptions |
The model targets 20% EBITDA after fair-market owner pay and treats 10% as the danger line. Compare each complete company case with those references. Neither percentage establishes whether cash arrives before payroll or whether a delivery role can cover the work.
Update the Decision When an Input Changes
Keep a short assumption register with the responsible person and the record behind each input. The sales owner updates expected starts, the service lead updates delivery demand, and the bookkeeper updates payments and commitments. Preserve the prior case so changes remain explainable.
Revisit the scenarios when a material assumption changes rather than letting the annual plan become a fixed promise. A delayed start, a departing client, or a new supplier commitment should change the relevant rows and the decisions tied to them.
Choose the next commitment from the combined view of earnings, cash, and work. If it survives only under an unconfirmed assumption, keep that condition visible and decide whether to wait, reduce the commitment, or fund the exposure deliberately.

mspoutpost.com/articles/financial-scenario-planning-for-an-msp-hiring-decision
Written by Graham Whitfield
MSP Outpost publishes information, not legal, financial, insurance, tax or compliance advice, and reading it creates no professional relationship. For decisions about your business, talk to a qualified professional.