
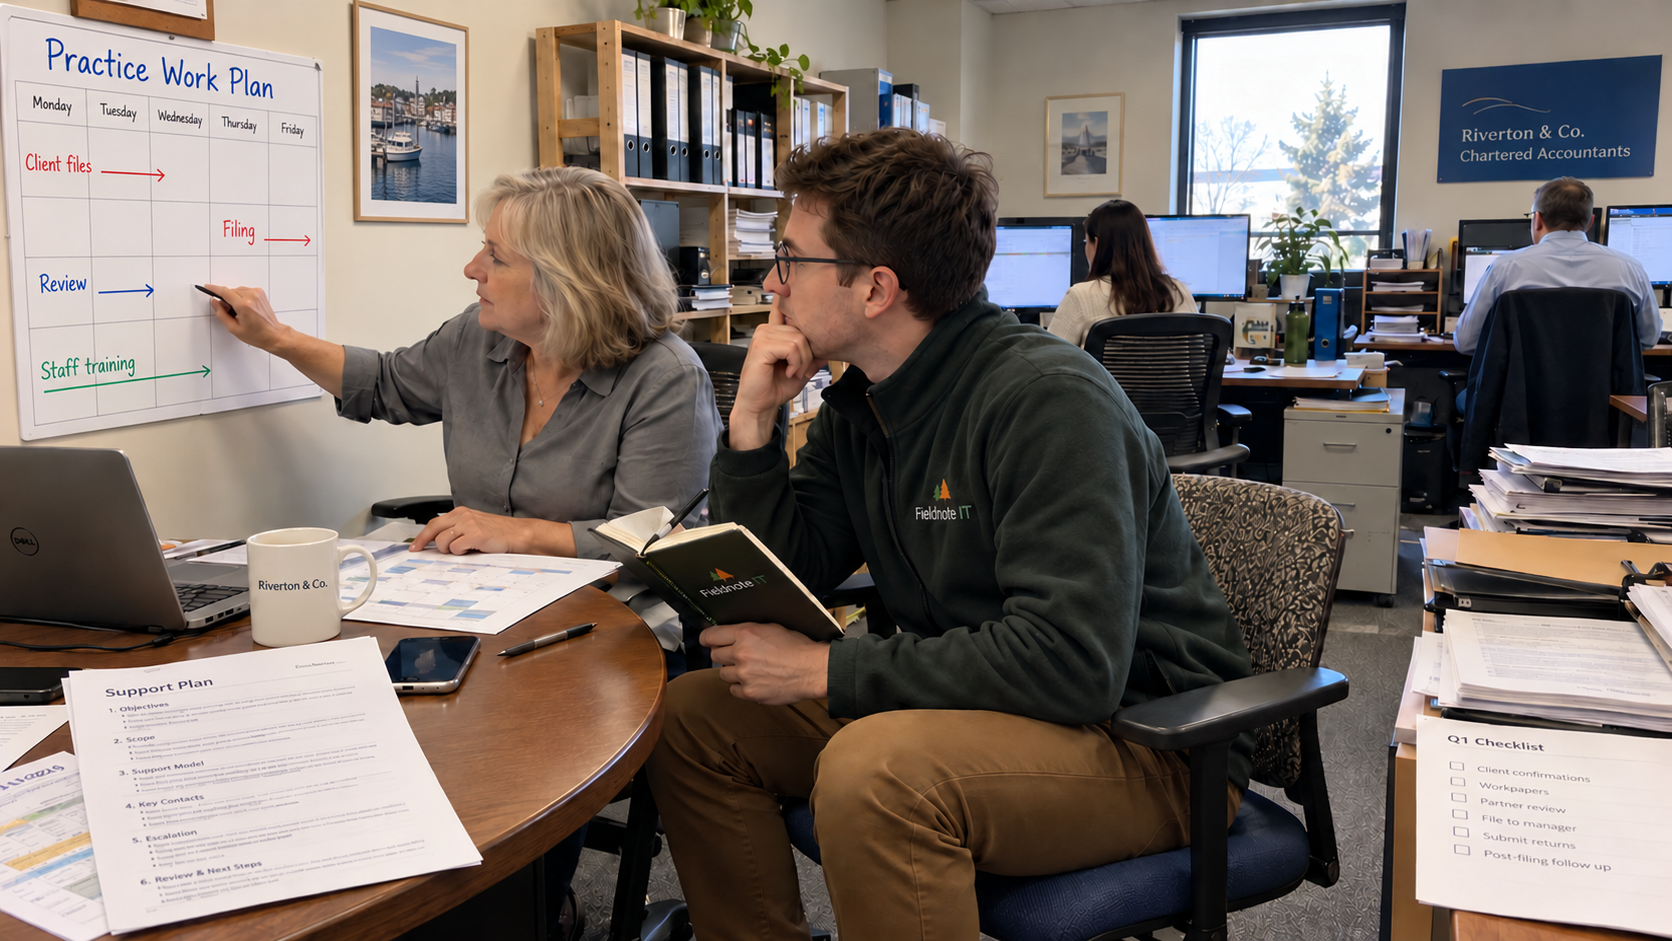
Picture a proposed offer that says 'priority IT support for accounting firms.' Replace it with an agreed busy-period plan that names the support hours and the person who can authorize an urgent change. The second offer gives delivery something to verify before marketing puts it on the website.
I'd build the service around the firm's actual calendar and the work it needs to complete. Then price the scope you can staff. Calling a package tax-season ready doesn't create another available engineer.
Ask for the Firm's Calendar Before Writing Yours
Have the account owner identify the client's busy periods with the person who runs its work. Ask which activities need reliable access and when staff will be working outside their normal pattern. Keep those answers with the account record instead of treating a public filing date as the whole operating calendar.
Paul Green suggests shaping an accounting offer around busy filing periods, including earlier health checks and an account contact who knows the client's deadlines. That is his sector-marketing suggestion. I'd turn it into specific account tasks before using it as a positioning claim.
Ask the client to identify the systems that support those activities and who owns each vendor relationship. Your standard stack still needs a clear boundary with the firm's specialist applications. A calendar entry cannot establish that your team supports software it hasn't agreed to cover.
Turn Priority Into a Defined Service
Here is what I'd cut: 'We understand accountants, so you always come first.' It makes a promise the dispatch team has no clear way to apply alongside its other client commitments. Describe the actual service arrangement instead.
| Proposed Marketing Line | Service Detail Needed Before You Publish It |
|---|---|
| Priority support during busy periods | State the agreed support window and the route used to assess an urgent request. |
| We know your accounting software | Name the applications the MSP supports and the boundary with the application vendor. |
| Changes scheduled around your deadlines | Record the client-approved restricted-change period and the process for exceptions. |
| A contact who understands your firm | Name the account responsibility and the cover when that person is unavailable. |
Keep response commitments tied to the agreement and the work your team can deliver. Don't offer an unqualified queue jump to every accounting prospect. The published claim needs to agree with the service delivered to the existing book.
Marketing cannot fix a missing support shift or an unresolved vendor boundary. If the delivery lead cannot explain how a promise is staffed, remove that promise until the work has an owner and capacity.
Prepare Before the Restricted-Change Period
Have the technical lead turn the firm's calendar into a readiness review. Check the agreed service dependencies and record remediation as assigned work. The readiness result should show what was verified and what still requires a client decision.
Define a restricted-change period as a client-agreed limit on elective changes during the specified work window. Keep a route for necessary security or recovery changes, with authority and testing appropriate to the action. 'We freeze everything' is not an adequate description of that decision.
For each proposed deferral, record what is postponed and who accepts the scheduling decision. Give urgent exceptions a named owner rather than leaving an engineer to interpret a slogan about avoiding disruption. Review the deferred work when the agreed restriction ends.
Don't package basic security as a seasonal luxury. The MSP model includes baseline security in every plan. For a tax-practice client, connect the actual service responsibilities with its security planning rather than promising compliance from the package name.
Ask the firm's responsible person which work your MSP owns. A service proposal should identify its contribution, not imply it establishes the firm's whole compliance position.
Price the Coverage You Actually Agree to Provide
The model's flat monthly fee comes with a plain explanation of inclusions and exclusions. Use that principle for the busy-period arrangement. Decide which preparation and support belong in the ongoing service, and identify any separate project or additional coverage before quoting it.
As a model illustration, 20 seats at the US $225 monthly goal produce a $4,500 fee. That figure doesn't price an unspecified extension of support hours. Cost the actual scope before deciding whether the proposed monthly fee can carry it.
Managed-service gross margin includes burdened delivery labor and tools, with a 50% model target. Include the work of covering the promised window in that calculation. A fee that appears adequate only because the additional labor is missing is an incomplete quote.
Avoid inventing a seasonal premium from a competitor's label. State any agreed additional work and its charging basis, while keeping included service inside the monthly fee. The client should be able to understand the offer before its busy period starts.
Measure the Promise Through the Work Record
Record qualified accounting inquiries and the service requested in the CRM. Keep the definition of qualified consistent so a change in website traffic is not reported as evidence that this offer fits the market. Link the eventual proposal to the coverage that delivery approved.
In the PSA, identify the accounting client's agreed busy-period work and record actual labor against it. Compare that effort with the work and coverage in the approved plan. Have the service lead examine an exception before attributing it to the sector itself.
My decision test is the coverage gap: required staffed support hours minus the hours actually available for that work. If required coverage exceeds available staffing, I would withdraw the unsupported promise until the gap is resolved. A higher inquiry count would not change that decision.
After the period, compare the planned service with the actual exceptions and client feedback. Check whether a problem came from the offer, an environment issue, or a missed handoff before changing the price. A busier queue by itself cannot tell you which explanation is right.
Use the Service Plan as the Proof of the Positioning
Before, the prospect sees a claim that the MSP understands accountants. After, they can examine the proposed working arrangement against their own deadlines. Publish only the version your team can explain and deliver.
Start with an existing accounting client willing to review its next busy period with you. Have the account owner and service lead agree the scope and confirm the available coverage. Then rewrite the offer from that plan, with its actual limits intact.
mspoutpost.com/articles/it-support-for-accounting-firms-that-fits-busy-periods
Written by Owen Gallagher
MSP Outpost publishes information, not legal, financial, insurance, tax or compliance advice, and reading it creates no professional relationship. For decisions about your business, talk to a qualified professional.