
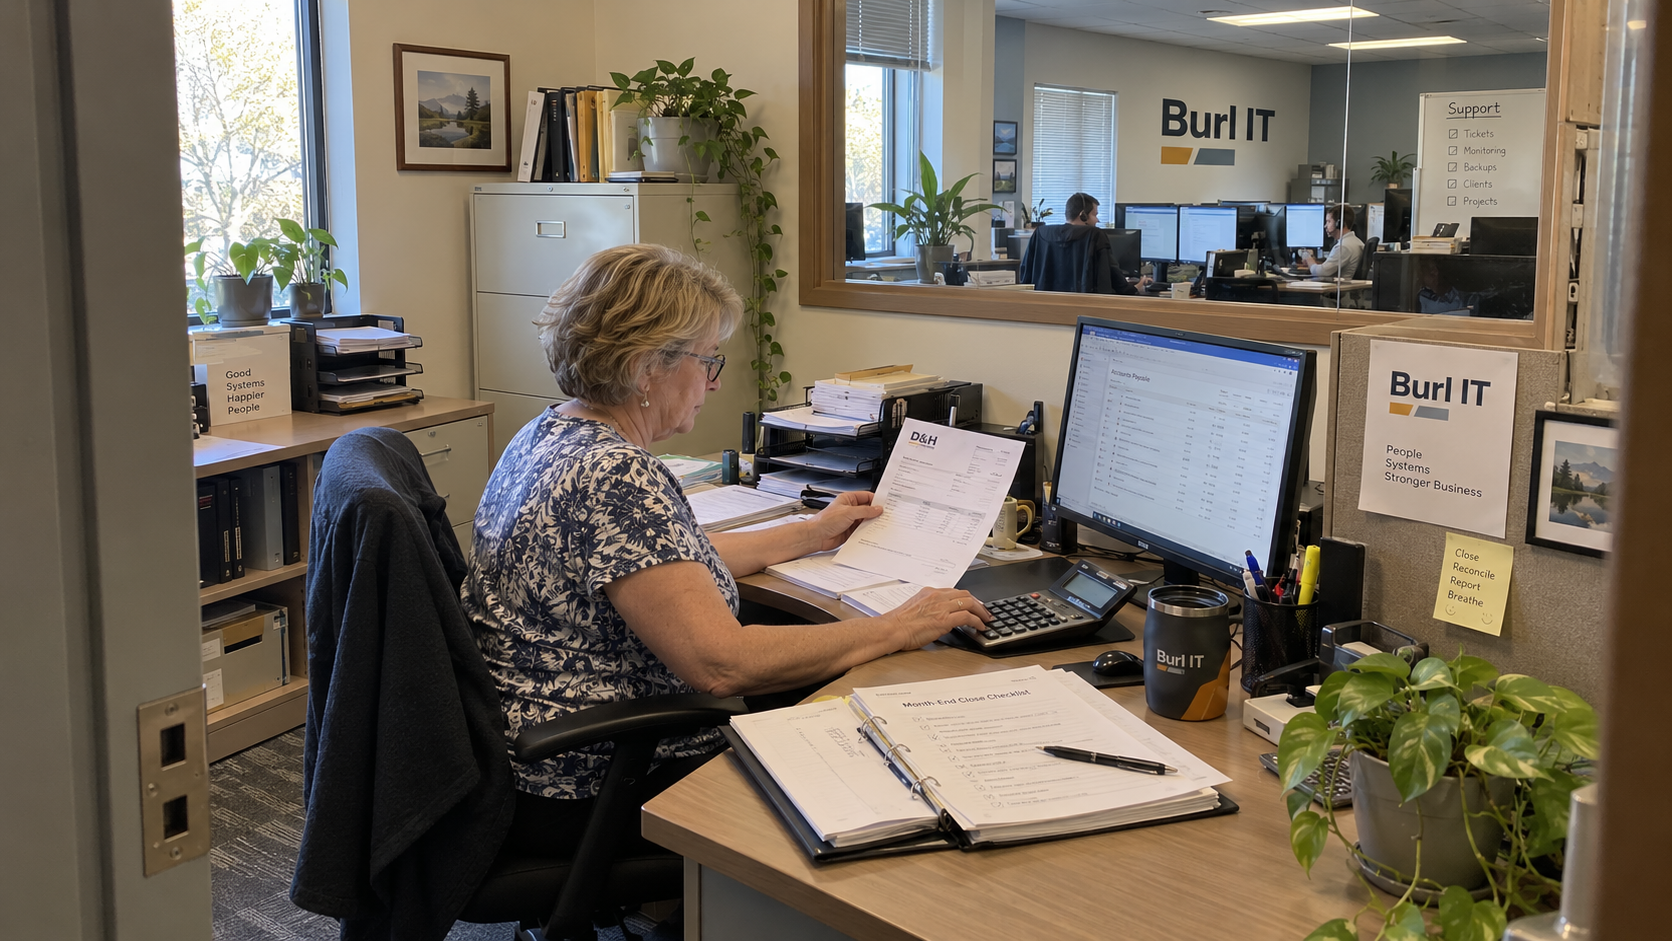
Assume the model's US bookkeeper role: $50,000 annual salary at full time, a 1.25 burden multiplier for the included employer payroll costs, and 0.5 of a full-time position. The US example budgets that role at $31,250 a year: $50,000 × 1.25 × 0.5. Your month end close checklist has to fit inside that person's actual assignment, alongside the billing work.
That is a staffing assumption, not a quote for an outsourced bookkeeper or a measured close duration. If your transaction volume or the work assigned differs, size the role again. I'd agree an owner-reviewed reporting date with the bookkeeper and accountant, then work backward through the information each needs.
A month-end close is the process of completing and checking the accounting records for the month before using its reports. Sending the invoices does not finish that job.
Agree What the Bookkeeper Can Close
Have the accountant confirm the accounting basis and the required treatment of month-end adjustments. Accrual accounting records revenue when earned and expenses when incurred, rather than simply when cash moves. Keep the management reports on the agreed basis so the comparisons mean something.
The bookkeeper should have an approved coding guide and a reviewer for decisions outside it. Coding means assigning a transaction to its accounting category. Don't ask the person entering vendor bills to invent your revenue policy when a project crosses the reporting boundary.
Set a submission deadline for the people providing records and a review slot for whoever signs off the pack. Base the dates on when those inputs become available and the time the work takes. A promise to close quickly is not an allocation of bookkeeper time.
Use a Short Checklist With Evidence Behind It
I'd keep the close record short and link each completed line to its supporting work. Assign a named person to the role shown below, including cover for an absence. An unchecked line needs an explanation and an owner before you rely on the reports.
| Close Check | Owner | Evidence to Review |
|---|---|---|
| Confirm the period inputs | Bookkeeper, with service and sales owners | The agreed source records are received, with missing items assigned. |
| Resolve billing exceptions | Billing owner | Contract changes and unbilled approved work have a recorded disposition. |
| Check delivery costs | Bookkeeper, with delivery owner | Supplier costs and payroll treatment follow the approved categories. |
| Review timing adjustments | Accountant or authorized reviewer | The calculation and treatment of each required adjustment are supported. |
| Reconcile the accounts | Bookkeeper | Statement checks and supporting balances explain the remaining differences. |
| Review the report pack | Owner and accountant as agreed | Corrections or explanations are resolved, and the pack has a clear status. |
Keep the checklist in the accounting workflow rather than distributing approvals across private messages. The bookkeeper records the blocker; the person who holds the missing information resolves it. Escalate an absent project record to the delivery owner instead of asking accounts to reconstruct the project from memory.
Close the Gap Between the PSA and the Books
Have the billing owner reconcile the period's approved agreement changes with the accounting records. For each exception, establish the authorized effective date and the treatment under your billing terms. Don't treat a change to a technical tool as proof that the corresponding commercial record changed.
Allan Michelmore describes using an accounts child ticket when an end-user onboarding or offboarding request changes the agreement or a tool outside the PSA integration. That is his workflow account. It gives you a useful place to look for a change that was completed technically but never reached billing.
Check approved project work that has not reached the accounting process with the project owner. Keep a disputed invoice under its recorded dispute rather than assuming an issued invoice resolves the disagreement. The accountant decides any required financial adjustment under the policy you've agreed.
Make Delivery Cost Comparable to Delivery Revenue
The model defines managed-services gross margin as revenue less burdened delivery labor and tools, divided by that revenue. A margin report that omits a supplier bill is answering a different question. Have the delivery owner confirm what was used while the bookkeeper applies the approved accounting treatment.
For a hypothetical month with the model's 700 seats held constant, use its $22.50 managed-service tool allowance per seat. Calculate the monthly planning amount as 700 × $22.50 = $15,750. Compare that planning amount with the recorded costs and explain differences from the actual licensed scope; don't enter the budget as if it were the supplier's bill.
Keep resold product costs separate from the MSP's internal delivery tools. Otherwise you can count the same cost against the managed seat and the product line. An unexpected margin is a reason to inspect the classification before assuming delivery improved or deteriorated.
Have the payroll owner confirm that the approved payroll information reached the books. Keep delivery labor in the relevant service cost and overhead roles in their assigned categories. The model places the half-time bookkeeper in general and administrative overhead, outside managed-services gross margin.
Give Missing Bills an Accounting Decision
An accrual is an estimate for an expense incurred before its bill arrives. Have the bookkeeper identify a missing supplier bill and give the accountant the service-period evidence needed to decide its treatment.
A prepayment is a payment for a benefit received in a future period. Have the reviewer check the period covered by an annual supplier charge instead of assuming that its payment date settles the monthly expense.
Record the reason and supporting calculation for an approved adjustment. Also record how the estimate will be cleared or reversed when the actual bill arrives, under the accountant's instructions. Check the prior adjustment when recording the bill.
Finish the Reconciliations Before Calling the Pack Final
Reconciliation means comparing the recorded balance with its supporting records and explaining the differences.
Have the bookkeeper retain the relevant statements and the reconciliation result. Give each unresolved difference a specific explanation for the reviewer. Don't create an unsupported balancing entry merely to make the task look complete.
Accounts receivable is the amount customers owe; accounts payable is the amount owed on supplier bills. Keep collection actions and supplier disputes attached to the relevant balance so the owner knows what remains to resolve.
Review the Reports and Control Later Changes
I'd ask the owner to review the profit and loss report, which shows the period's income and expenses, alongside the balance sheet, which shows assets and obligations at a point in time. Include a cash-flow view so a profit figure doesn't substitute for the cash available. Use the accountant's agreed report pack and comparison basis.
For each unexpected result, record the explanation or correction and its owner. Compare like periods and identify any changed classification before crediting a better margin to the desk. The service owner should answer for an unexplained delivery-cost movement; the bookkeeper should not have to invent an operational explanation.
Have the authorized reviewer mark the pack final only after the required checks and decisions. Keep provisional reports clearly identified while an unresolved item could change them. Agree who may amend a closed period and how a correction reaches people who received the earlier version.
Before the next close, inspect the last pack's blockers with the bookkeeper. Assign the missing inputs to the people who can actually provide them and reserve the review time. Judge the routine by supported reports delivered on the date you've agreed, rather than by how confidently someone says the books are done.

mspoutpost.com/articles/month-end-close-checklist-for-an-msp-bookkeeper
Written by Graham Whitfield
MSP Outpost publishes information, not legal, financial, insurance, tax or compliance advice, and reading it creates no professional relationship. For decisions about your business, talk to a qualified professional.