
Assume the US model's annual revenue of $3,634,615 and its payment-fee allowance of 0.4% of revenue. Calculate the allowance as $3,634,615 x 0.4%, which the model rounds to $14,538 a year. Passing credit card fees to customers needs a separate calculation and a permitted collection method. The allowance isn't a card-processing rate to add to an invoice.
That 0.4% is the model's planning assumption for card and ACH fees, not a measured industry average. It covers collections across the business, including hardware sales. Start with your statements before deciding whether the MSP absorbs the cost or changes the payment arrangement.
Measure the Cost on the Right Basis
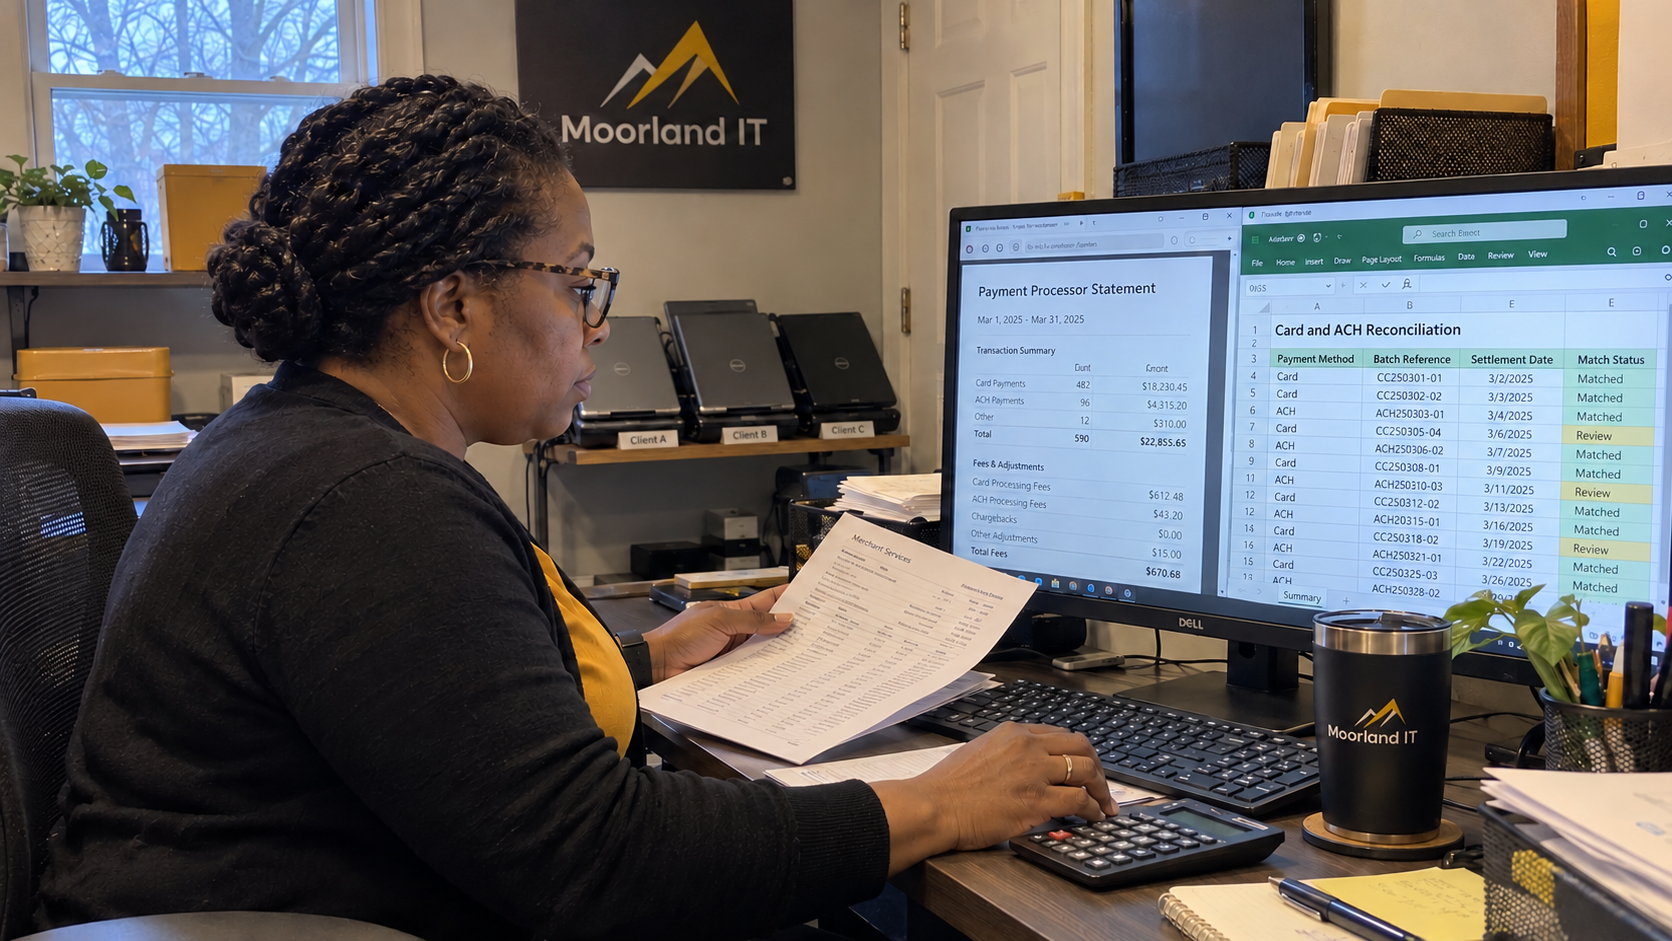
Reconcile the processor statements with payments recorded in your accounts for the same period. Separate the card activity from bank collections. Keep charges taken out of settlements visible rather than treating the net deposit as the original payment amount.
An effective processing rate is the processing cost divided by the payment volume on the same basis. Your overall fee share of revenue uses total business revenue instead. Don't compare those percentages as though they describe the same thing.
| Calculation | Inputs to Use | What It Helps You Decide |
|---|---|---|
| Business Payment-Fee Share | Total card and ACH fees divided by total business revenue for the same period. | How actual fees compare with the model’s 0.4% planning allowance. |
| Card Cost on Card Volume | Card fees divided by the card payment volume to which they relate. | What the card channel actually costs before any permitted recovery. |
| ACH Cost on ACH Volume | ACH fees divided by the related bank collection volume. | Whether your actual bank route costs less for the proposed payment mix. |
| Merchant-Retained Direct Fees | Actual processing fees less any permitted surcharge amounts actually collected. | How much direct fee cost remains with the MSP. |
Review the underlying fee lines as well as the total. A fixed transaction charge and a recurring platform charge affect different payment patterns. Check which charges are already included before adding a software cost again.
Keep staff effort alongside the direct-fee comparison, with its own cost basis. A cheaper transaction method can still need exception handling and reconciliation. A rule of thumb isn't a processor statement.
Compare the Payment Arrangement Before Moving Clients
I'd compare the actual cost of keeping the existing arrangement with the proposed mix. Use the client's expected payment amounts and the processor's current terms. Don't insert a generic card rate or assume bank debit is free.
For a proposed shift to ACH, calculate the fees for that volume under your actual agreement. Include any setup or ongoing charges that apply, without counting charges already included elsewhere. Then show the difference from the current cost for the same work.
Choose the clients whose payment pattern and purchasing process fit the bank route. Recurring invoices may make that arrangement worth discussing, but the client still needs an authorized person who can approve it. Don't turn a payment-method preference into an unannounced change at the next invoice.
Keep the managed-service fee tied to its agreed scope. Explain the payment method separately and record the client's accepted arrangement. A collection change shouldn't quietly rewrite the service commitment.
Check Whether a Card Surcharge Is Permitted
A surcharge is an extra charge for paying by a particular card method. Before enabling one, have your processor confirm the requirements for your merchant arrangement and the card brands you accept. Have the applicable jurisdiction and contract position checked before changing the client terms.
Have the processor confirm the requirements separately for each accepted card type rather than treating a credit-card rule as permission to surcharge every payment.
Ask the processor to confirm the permitted amount and the applicable disclosure and notification process. Give them the actual payment channels you use. Don't copy another merchant's surcharge percentage and assume it fits your costs or accepted cards.
Have the billing owner test the configured checkout and receipt through the provider's approved process. Check eligible and ineligible payment types, along with how adjustments are handled. A switch in the billing application doesn't establish that the arrangement meets every requirement.
Keep the approved client wording with the configuration record. Tell clients what they will see before the first affected payment. Give the person answering billing questions the same explanation so the invoice doesn't introduce a policy nobody can describe.
Set up Bank Collections as an Authorized Process
ACH is the US bank-payment network used for electronic credits and debits. A debit pulls funds from the customer's account under an authorized arrangement.
Use the provider's process for obtaining and retaining the required authorization. Confirm the process appropriate to the customer's account and payment arrangement rather than copying a consumer form without checking it.
Have the billing owner confirm when the approved collection will run and how it appears to the client. Verify the route for a failed or returned payment with the provider. Keep that exception attached to the invoice so an unresolved collection doesn't disappear from the accounts work.
Check the first affected collection through reconciliation before assuming the move is complete. Prevent the old recurring method from charging the same invoice. The saving needs a working payment process behind it, not just a lower rate in the comparison.
Decide What Cost the MSP Will Carry
Compare the arrangements using the same revenue and payment period. State which direct fees remain with the MSP after any permitted recovery. Keep a surcharge actually collected separate from the amount the billing system was configured to request.
Then compare the cost of administering each arrangement. Ask the billing owner to identify exceptions that required manual follow-up. A smaller fee line alone doesn't establish a better result if it also leaves unpaid invoices or unresolved client disputes.
Use the model allowance to expose a difference that needs explanation. If your fee share is higher, investigate the payment mix and statement detail. If it is lower, check that the ledger includes all the fees before deciding the process is unusually efficient.
I'd keep the final decision with the owner responsible for pricing and the person who runs billing. They need the actual cost comparison and the confirmed terms. The desk shouldn't be negotiating an extra collection charge while trying to resolve a service request.
Review the Result After the Change
Record payment-method changes against the affected clients. Have finance reconcile the resulting fees and receipts on the same basis as the original comparison. Check payment exceptions alongside the cost difference.
If the expected saving doesn't appear, rebuild the calculation from the actual transactions. Check whether the planned clients moved and whether additional charges explain the result. Don't declare a policy successful from the number of clients invited to use it.
Start with your current processor statement and total revenue for the same period. Reconcile the costs, compare the actual alternatives, and confirm the permitted process before enabling an extra fee. The decision should survive a calculation your billing owner can reproduce.

mspoutpost.com/articles/passing-credit-card-fees-to-customers-check-msp-costs
Written by Graham Whitfield
MSP Outpost publishes information, not legal, financial, insurance, tax or compliance advice, and reading it creates no professional relationship. For decisions about your business, talk to a qualified professional.