
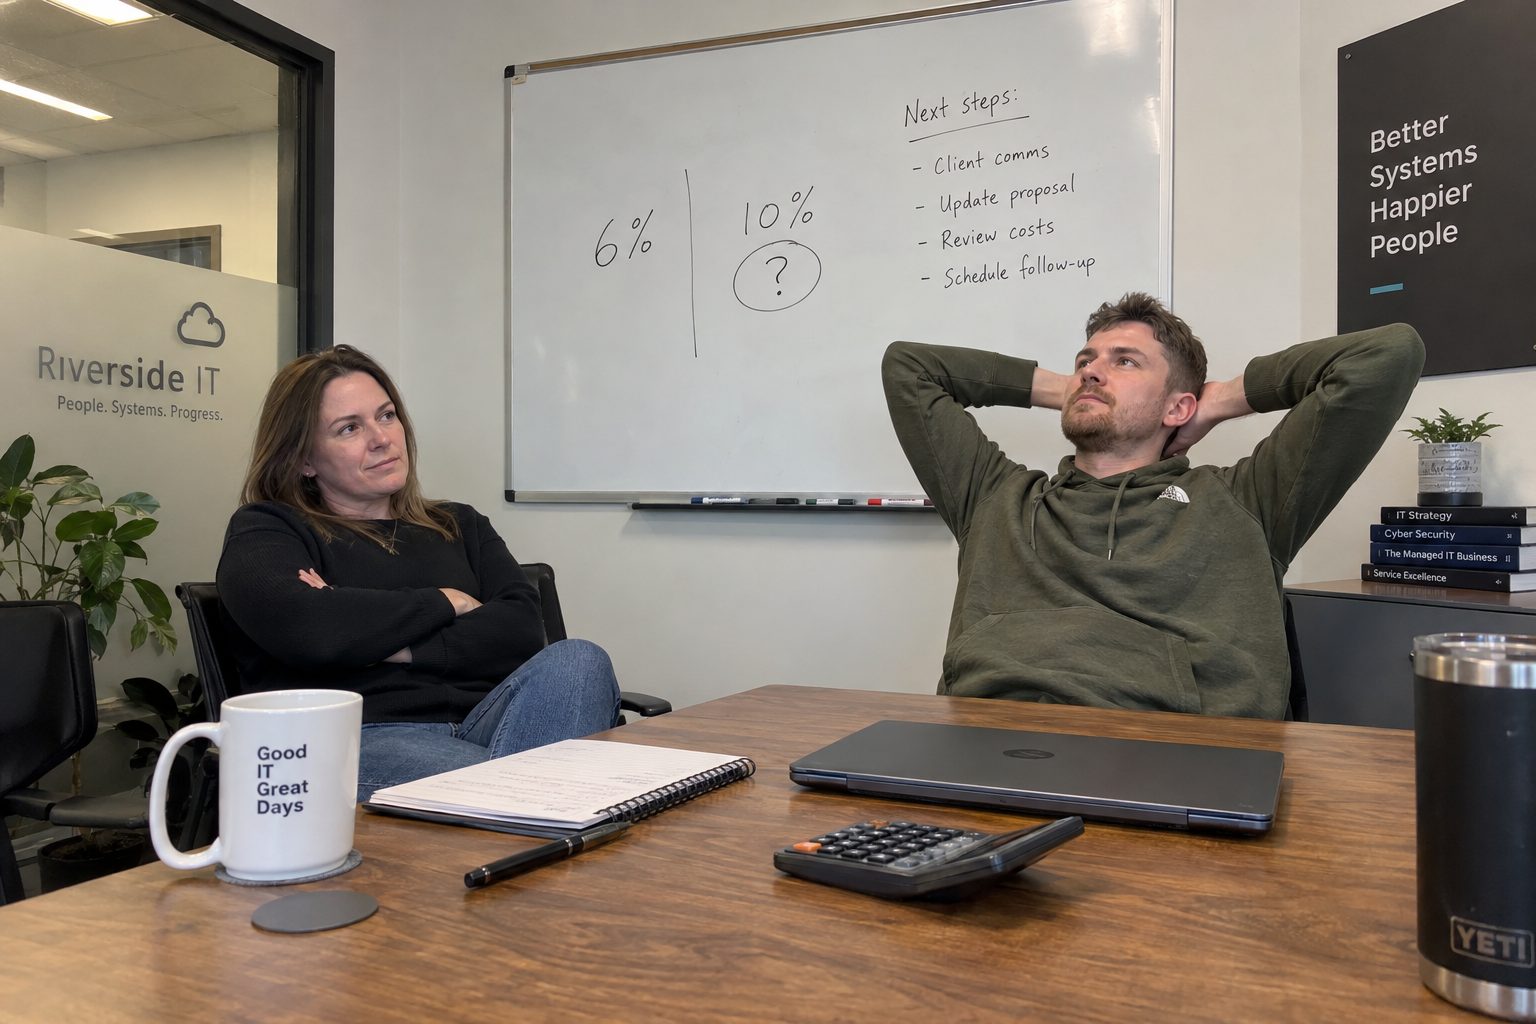
Budget 6% of revenue for sales and marketing in the MSP model's stable setting, or 10% for its faster-growth setting. Then check the clients, delivery work, and profit that each budget assumes. Spending the percentage alone doesn't promise the result.
Say you're choosing between those budgets for the model's US MSP: 35 clients, 700 seats, and about $3.6 million in annual revenue. The choice takes bottom-up EBITDA from about 20.1% to 15.0%. I'd make that trade explicit before approving the spend.
Count the Rep Before the Campaigns
Sales and marketing includes the people doing the selling. In the stable example, the annual budget is $218,077. The sales rep costs $137,500 at burdened pay, leaving $80,577 for programs and events.
Those programs are inside the budget. Don't approve the full percentage for campaigns and add the rep afterward. Ask whoever prepares the budget: 'Does this total include the person who has to turn the interest into signed clients?'
The growth setting adds a marketing coordinator alongside the rep. Their combined burdened cost is $212,500, within a $363,462 sales-and-marketing budget. That leaves $150,962 for programs and events, rather than making the coordinator an extra expense outside the percentage.
Turn the Budget Into a Client Target
The model allows $25,000 to acquire a new managed client. It calculates acquisition cost by dividing the whole sales-and-marketing spend by new clients won. That is an allocation of the annual budget, not a quote for the next lead or the cash cost of closing one more deal.
Divide each budget by that acquisition cost and you get the modeled pace. The comparison below holds the starting revenue and delivery assumptions constant while changing the growth spending and its associated costs.
| Annual Comparison | Stable Setting | Growth Setting |
|---|---|---|
| Sales and marketing as a share of total revenue | 6% | 10% |
| Sales and marketing budget | $218,077 | $363,462 |
| Burdened sales and marketing people | $137,500 | $212,500 |
| Programs and events | $80,577 | $150,962 |
| Modeled new managed clients | 8.7 | 14.5 |
| Modeled managed services growth | 12.2% | 20.3% |
| Bottom-up EBITDA margin | 20.1% | 15.0% |
A fractional client is a planning average, not a sales instruction. Give the rep the underlying assumptions and agree how you'll judge the actual results. A useful budget conversation starts with: 'What would have to be true about our acquisition cost to reach this pace?'
Use the same spending definition when you compare the plan with your results. If you leave the rep out of actual acquisition cost while including that pay in the budget, the comparison is wrong before you've assessed a campaign.
Check the Value of the New Clients
A new client starts at $2,200 MRR in the model. The existing book averages $4,500 per client, so counting every new win at the installed-base average would overstate the modeled addition. Ask the rep: 'What recurring amount are we actually signing at the start of the agreement?'
The growth calculation annualizes that starting MRR. It adds the annual price step of 5% and subtracts the loss assumption associated with 95% annual retention. In that simplified calculation, the price step and loss allowance offset each other, leaving the new-client contribution to produce the growth figures in the table.
That is a comparison of modeled annualized revenue, not a promise of cash collected during the budget year. When you sign a client matters to the collections forecast. Use expected start dates and payment terms when you test whether the bank balance can carry the spending.
The stable label also needs reading carefully. Its 12.2% managed services growth sits below the model's 14% minimum growth ambition; the goal is 25%, with 40% as the stretch. These are planning targets, not results the spending percentages guarantee.
Give the Onboarding Work an Owner
More wins bring more work beyond selling. The model assigns 60 hours of project-engineer time to each new client and waives the onboarding fee after quoting it. Delivery still has to pay for those hours.
Put the onboarding hours with project delivery, alongside the work clients already pay for.
I'd put the project lead in the budget discussion before committing to the faster pace. Say: 'Show me where these onboardings fit beside the projects we've already promised.' Name who owns the migrations and what you would reschedule if the starts overlap.
Keep the rep responsible for new business and account managers responsible for the existing book. That's the model's separation of roles. If your plan needs the hunter to spend their selling time on delivery or account work, revise the capacity assumption before treating the client target as funded.
Read the Profit Cost With the Growth Target
The extra sales-and-marketing allocation accounts for four percentage points of revenue. The total EBITDA difference is about 5.1 points, including the additional unpaid onboarding in the growth setting. The coordinator is already inside the sales-and-marketing total; counting that pay again would overstate the cost.
Use the bottom-up result when you decide what the business can support. It includes the named roles and overhead, including a fair-market owner salary before profit. A budget that balances to a target doesn't replace that costing.
My view: stay with the stable setting while you fix delivery problems or work out how the next onboardings will be covered. Consider the growth setting when those responsibilities are assigned and you deliberately accept the modeled profit trade. The model's 20% EBITDA target should stay visible in that decision.
Set the Conditions for Spending More
Before authorizing a larger budget, I'd agree the checks with the people responsible for carrying it out:
- The owner approves the total spending and the resulting profit forecast.
- The sales lead records new clients won and their starting MRR against the acquisition-cost assumption.
- The project lead assigns onboarding work alongside the existing project commitments.
- The person responsible for the cash forecast checks collection dates against payroll and program payments.
If actual acquisition cost is above the assumption, inspect the underlying deals and spending before deciding whether to increase the budget. Check the fit of the prospects and what happened between discovery and a decision. The ratio tells you the plan missed; it doesn't identify the cause by itself.
Finish the budget meeting with a decision your team can use: 'We are approving this spending at this client pace, with this delivery plan and this profit forecast.' If one of those assumptions changes, bring the choice back for review. Then your percentage has a job beyond filling a line in the spreadsheet.
mspoutpost.com/articles/how-much-to-spend-on-sales-and-marketing-6-to-hold-10-to-grow
Written by Natalie Brandt
MSP Outpost publishes information, not legal, financial, insurance, tax or compliance advice, and reading it creates no professional relationship. For decisions about your business, talk to a qualified professional.