
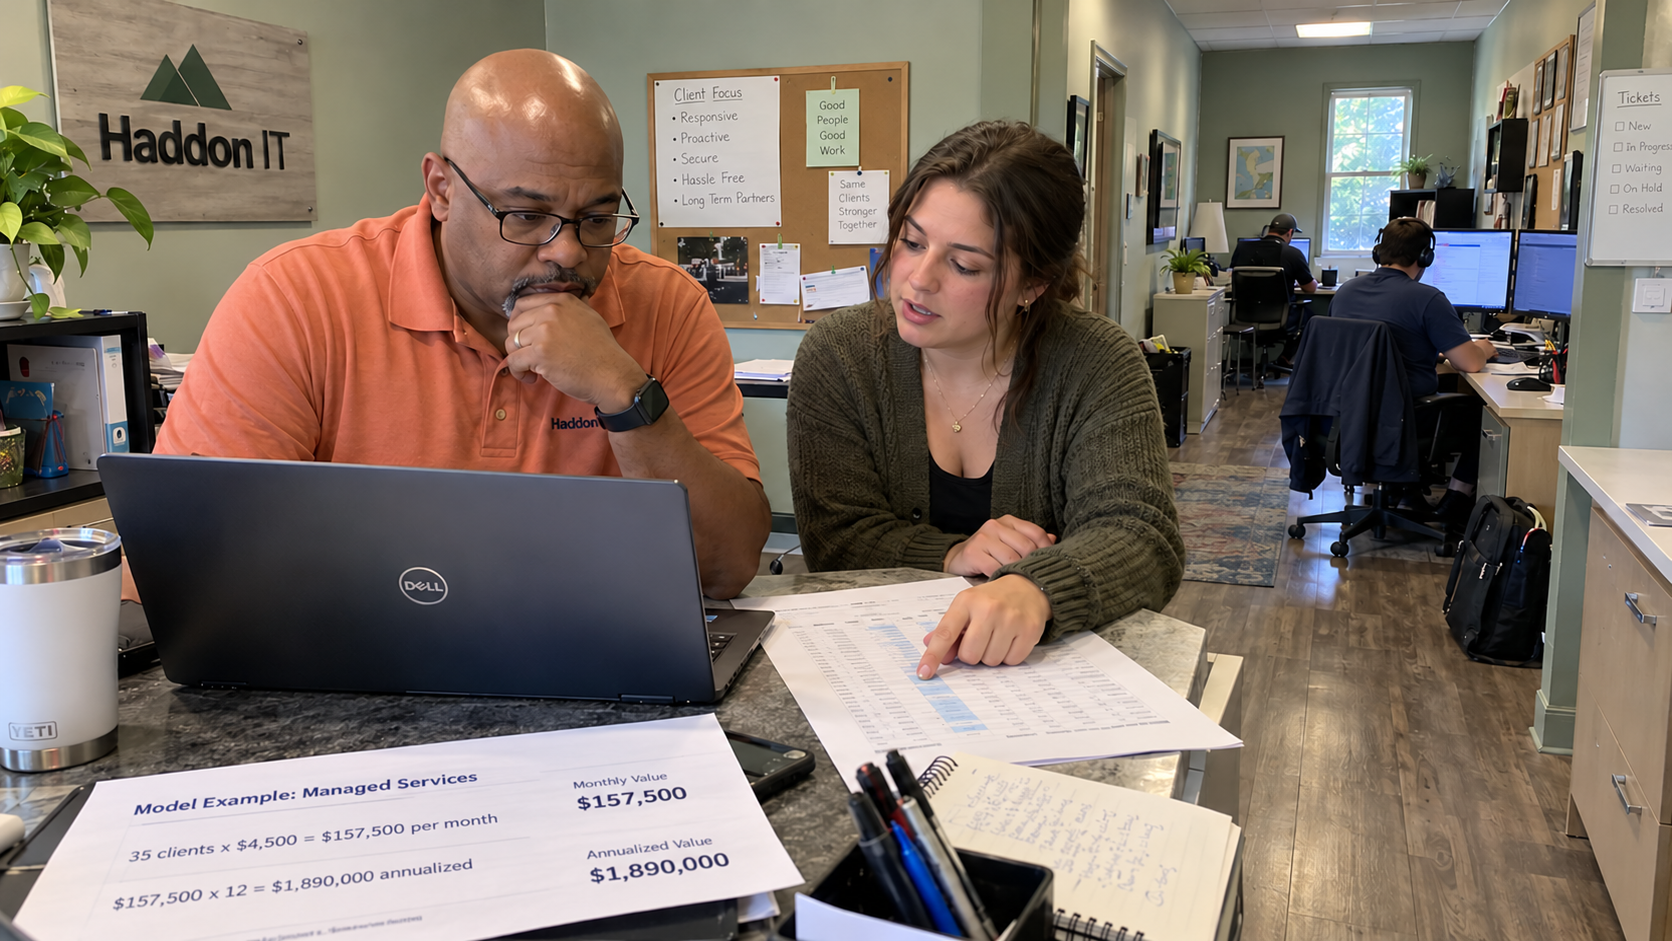
Assume the US model's 35 clients each pay its $4,500 monthly managed-service fee. The book is 35 × $4,500 = $157,500 a month, and $157,500 × 12 = $1,890,000 annualized. MRR vs ARR changes the reporting period, not the size of that book.
Monthly recurring revenue, or MRR, is the monthly value of the active recurring services included in your measure. Annual recurring revenue, or ARR, expresses that same value annually, using MRR multiplied by 12 here. Neither operating measure predicts the coming year's recognized revenue without accounting for changes in the book and their dates.
Keep the Revenue Boundary Beside the Total
The opening figure covers managed services only. The model also treats recurring product sales as recurring revenue. Keep that broader view separate, especially when a staffing ratio uses managed-service MRR rather than all recurring products.
The US example has $1,890,000 of annual managed-service revenue and $763,269 of recurring-product revenue. Annual recurring value is $1,890,000 + $763,269 = $2,653,269. Its monthly equivalent is ($1,890,000 + $763,269) ÷ 12 = $221,105.75, or about $221,106.
That product line explains the difference from $157,500 of service-only MRR. Exclude one-time hardware and project sales from this recurring measure. Document the treatment of any unusual item so the next report can be reconciled on the same boundary.
Record service starts and approved changes on their effective dates. Finance needs to connect the active agreement record to billing. The date money arrives belongs in the cash view; it doesn't supply the definition of recurring value.
Separate an Advance Payment From Service Value
For the illustrative client, an unchanged year at $4,500 monthly is $4,500 × 12 = $54,000. Collecting that amount in advance doesn't turn its monthly managed-service value into $54,000. Keep the collection and the monthly operating measure in their appropriate records.
An overdue receipt also needs a separate collection assessment. It doesn't automatically establish that the recurring agreement has ended. Apply the documented treatment and keep a doubtful account visible rather than silently changing the client count from payment timing.
My view is that the definitions should stay beside the report until the team can reproduce it. A rule of thumb won't reconcile different denominators. Agree the boundary before deciding which recurring total belongs in the discussion.
Retain the Opening Clients, Not the Closing Count
Annual client retention is the share of the opening clients still present at the end of the year. Divide retained opening relationships by the opening count. A new account belongs in growth, not in the numerator that measures whether an original client stayed.
Using the model's 95% annual client-retention input, 95 ÷ 100 = 0.95. For an illustrative plan with 35 opening clients, 35 × 0.95 = 33.25 retained relationships. The corresponding loss is 35 - 33.25 = 1.75, roughly two relationships for planning. Actual clients are whole relationships, so neither fractional result belongs in the observed retention report.
Keep account identity consistent through administrative changes. Investigate a merger or rename before recording a lost relationship and a new one. A larger closing book can coexist with original clients leaving; show those movements separately.
State the Assumption Behind Retained Revenue
Client retention counts relationships. Revenue retention measures the recurring value remaining from an opening group, with an explicit treatment of price and scope changes. Unequal client fees can make those results diverge.
For a deliberately equal-fee illustration, assume all 35 opening clients pay $4,500 and no fee or seat changes occur. Retained managed-service MRR is 35 × $4,500 × 95% = $149,625. Lost monthly value is (35 × $4,500) - (35 × $4,500 × 95%) = $7,875. Annualized lost value is [(35 × $4,500) - (35 × $4,500 × 95%)] × 12 = $94,500.
The equal-fee assumption is what permits the client-retention percentage to be applied to revenue in that illustration. It isn't a declaration that the model's 95% is gross revenue retention for every book. Use the actual opening clients and their fees when assessing your own retained value.
Keep expansion inside retained accounts separate from new-client revenue. State whether a revenue-retention measure includes expansion before comparing it with one that excludes it. A price increase can lift the original group's value while another relationship disappears.
Replace the Lost Value With the New-Client Input
The model's new-client MRR is $2,200, below the installed example's $4,500 average. To replace the equal-fee illustration's lost value, calculate [(35 × $4,500) - (35 × $4,500 × 95%)] ÷ $2,200 = about 3.58 replacement wins. If every win actually starts at $2,200, round up to four whole wins to cover that monthly gap.
Once active, four clients at that fee produce 4 × $2,200 = $8,800 a month. That is arithmetic from model inputs, not a prediction of signed prospects. Actual fees and start dates determine the value you can record.
It also doesn't put a full year's recurring equivalent into revenue immediately. A later start contributes for fewer periods in the year. Build the forecast from the actual service starts and endings rather than treating ARR as collected cash.
Reconcile the Monthly Movement
Use a movement record to explain how opening MRR becomes closing MRR. Keep product revenue separately reconcilable when it appears in the wider recurring view. Every movement needs an effective date and a supporting record.
| Movement | Supporting Record | Owner |
|---|---|---|
| Opening value | Prior closing book on the same definition | Finance |
| New clients | Active agreement and service start | Sales and account owner |
| Expansion | Approved existing-client price or scope increase | Account owner |
| Contraction | Approved reduction distinguished from a lost relationship | Account owner |
| Lost clients | Ending relationship and its recurring value | Account owner |
| Corrections | Explained data correction separate from commercial growth | Finance |
| Closing value | Opening value plus additions less reductions, reconciled with active services | Finance |
Nick Clift recommends explicit accountability for the managed-service relationship and contract economics. Melissa Hockenberry argues that the retention owner needs access to decision-makers and an audience for customer knowledge. Those are practitioner views on making the relationship work visible, rather than leaving retention as a finance-only percentage.
Start the next report with the reconciled opening group and its revenue definition. Have finance trace the movements while account owners verify relationship changes. Read the annualized value beside retention only when the assumptions and boundaries of both remain visible.

mspoutpost.com/articles/mrr-vs-arr-define-recurring-value-and-retention
Written by Graham Whitfield
MSP Outpost publishes information, not legal, financial, insurance, tax or compliance advice, and reading it creates no professional relationship. For decisions about your business, talk to a qualified professional.