Figures are in US dollars unless marked.
Reconcile MSP deferred revenue client by client before putting a sale schedule in front of a buyer. Start with the payment already received, identify the service still owed, and have your accountant reconcile that obligation to the books. A paid invoice proves collection; it doesn't show how much of the covered work is complete.
I'd keep the working schedule separate from the sale-price discussion until finance can reproduce its balance. In this schedule, deferred revenue means the part of an advance that your accountant assigns to service not yet earned. The accounting basis and the agreement decide which amounts belong there.
Fix the Basis Before Calculating the Balance
Ask the accountant to write down the basis used for the sale accounts before the team exports client balances. Keep that explanation with the schedule, including how the service period is measured. Don't let billing build an annual-payment report while finance answers a different question about earned revenue.
IRS Publication 538 distinguishes US tax reporting under the cash method, generally when income is received, from the accrual method, generally when it is earned. That distinction is a reason to ask your accountant which basis each report uses. Don't use a tax-method label as a substitute for a reviewed sale-accounting schedule.
Keep the tax discussion with the accountant rather than turning a spreadsheet formula into a tax election. The useful owner decision here is which client records support the balance you're presenting. Record an unresolved accounting question as unresolved, with a named person responsible for answering it.
Carry a Prepaid Client Through the Calculation
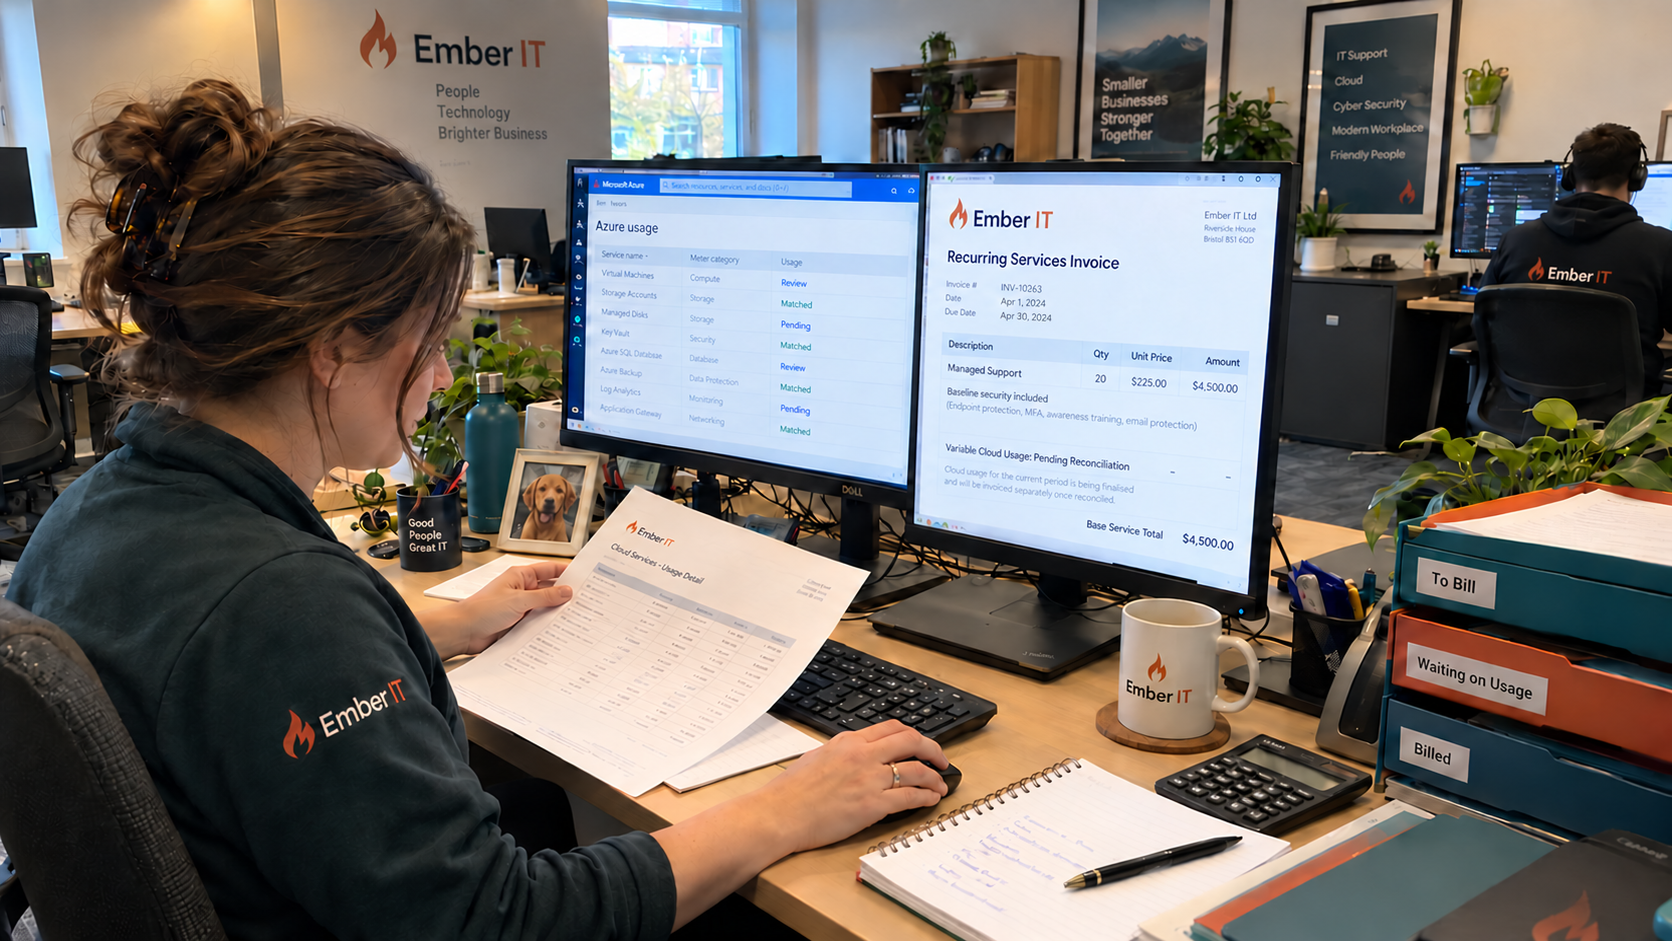
For a hypothetical US client, assume 20 seats at $225 per seat per month, an unchanged service scope, and full payment for 12 months. Assume the accountant approves earning this fee evenly over those months, with no separate products, taxes, credits, or price changes. If the arrangement differs, replace that assumption before using the result.
The monthly service amount is 20 seats × $225 = $4,500. The advance is $4,500 × 12 = $54,000. Suppose the review falls after three complete covered months; those months and the remaining nine are positions in this hypothetical agreement, not a standard sale timetable.
| Schedule Line | Working Under These Assumptions | Amount |
|---|---|---|
| Advance collected | 20 seats × $225 × 12 months | $54,000 |
| Service earned through review | 3 complete months × $4,500 | $13,500 |
| Remaining covered months | 12 months − 3 months | 9 months |
| Unearned service balance | $54,000 − $13,500 = 9 months × $4,500 | $40,500 |
For that assumed even-month allocation, $54,000 received − $13,500 earned = $40,500 still allocated to future service. The cash receipt hasn't changed. The schedule explains why treating the full deposit as earned service would disagree with the assumed allocation.
That $40,500 is a service-value balance under the stated assumptions, not a calculation of the labor still required or the cash you must reserve. Build the delivery forecast from the actual work and supplier commitments. Ask the accountant and transaction adviser to resolve how the reviewed balance enters the proposed deal rather than automatically deducting it from a price.
Make Every Client Row Traceable
Use a stable client identifier so finance can connect the schedule to the original invoice and payment. Keep the service-period record beside it. A bank entry alone won't tell the reviewer which client period the payment covers.
| Record to Keep | What the Reviewer Should Be Able to Check |
|---|---|
| Client and agreement reference | The actual service arrangement behind the row |
| Invoice and covered period | The charge and the service dates it describes |
| Cash receipt and payment reference | Whether and when the advance was collected |
| Allocation basis and completed period | How finance determined the amount earned |
| Credits and approved service changes | Why the balance differs from the original invoice |
| Ledger reference and review status | Where the amount appears and who checked it |
Keep each adjustment linked to its original record rather than replacing the invoice amount with a corrected total. For a changed seat count, retain the approved change and the effective service period. Let the accountant determine its treatment before the team recalculates the remaining amount.
Separate collected advances from invoices that remain unpaid. In the hypothetical calculation, collection was an explicit starting condition. If the cash hasn't arrived, mark the difference instead of presenting the invoice total as money already held.
Bridge the Client Schedule to the Closed Books
Have finance total the reviewed client rows and compare them with the corresponding balance in the closed books. A reconciliation is the explanation connecting those totals, including every difference still awaiting resolution. Keep the report version and the underlying ledger references together.
When the totals disagree, trace the difference rather than forcing the client schedule to match. Look for a payment mapped to the wrong period or an adjustment that appears in only one export. Those are investigation prompts, not a claim that either error exists in your accounts.
Rob Scott describes preparing an operational revenue report before the period ends, with accounting validating it afterward. I'd preserve that distinction in your own handoff: a useful early view can remain provisional. Give the buyer-facing schedule a separate reviewed version instead of quietly promoting the latest operating estimate.
Keep a change record when finance closes an open question. Show the old amount, the accepted amount, and the reason for the change. The reviewer should be able to follow the correction without asking which attachment superseded which.
Separate the Service Balance From the Deal Decision
Ask the buyer's team what supporting schedule they want and which transaction question it answers. Ray J. Green recommends asking likely buyers what characteristics they value when preparing a business for sale. I'd use that advice to agree the requested evidence before building a report nobody asked for.
Keep the calculation and the proposed transaction treatment in different columns. One explains the remaining service value on your chosen basis; the other records the advisers' agreed treatment in this particular deal. Don't let a label such as advance payment settle an unresolved commercial question.
Ask delivery to review the work that remains against the same client periods. Keep that forecast beside the finance schedule, with its own assumptions. An amount allocated to future service doesn't by itself say which technician hours or supplier bills remain.
A rule of thumb is a poor substitute for a client ledger. I'd rather see a difference explicitly awaiting an answer than a tidy total produced by an unexplained adjustment. Keep disputed items visible until the responsible reviewer resolves them.
Hand Over a Reviewed Balance and Its Explanation
Give the finance owner responsibility for the final schedule and the links to supporting records. Have the account owner confirm that the service scope still describes the agreement being delivered. Keep permission to change the accounting treatment with the accountant rather than the person assembling the export.
Before releasing the schedule, ask another reviewer to reconstruct the hypothetical client's $40,500 from its printed working: $54,000 − $13,500 = $40,500. Apply that same traceability test to your actual client rows, using their approved basis and real records. The deliverable is a balance another person can explain, with the remaining service and unresolved deal questions still attached.
mspoutpost.com/articles/msp-deferred-revenue-reconcile-advances-before-a-sale
Written by Graham Whitfield
MSP Outpost publishes information, not legal, financial, insurance, tax or compliance advice, and reading it creates no professional relationship. For decisions about your business, talk to a qualified professional.